By Kresmion Research, October 12, 2026
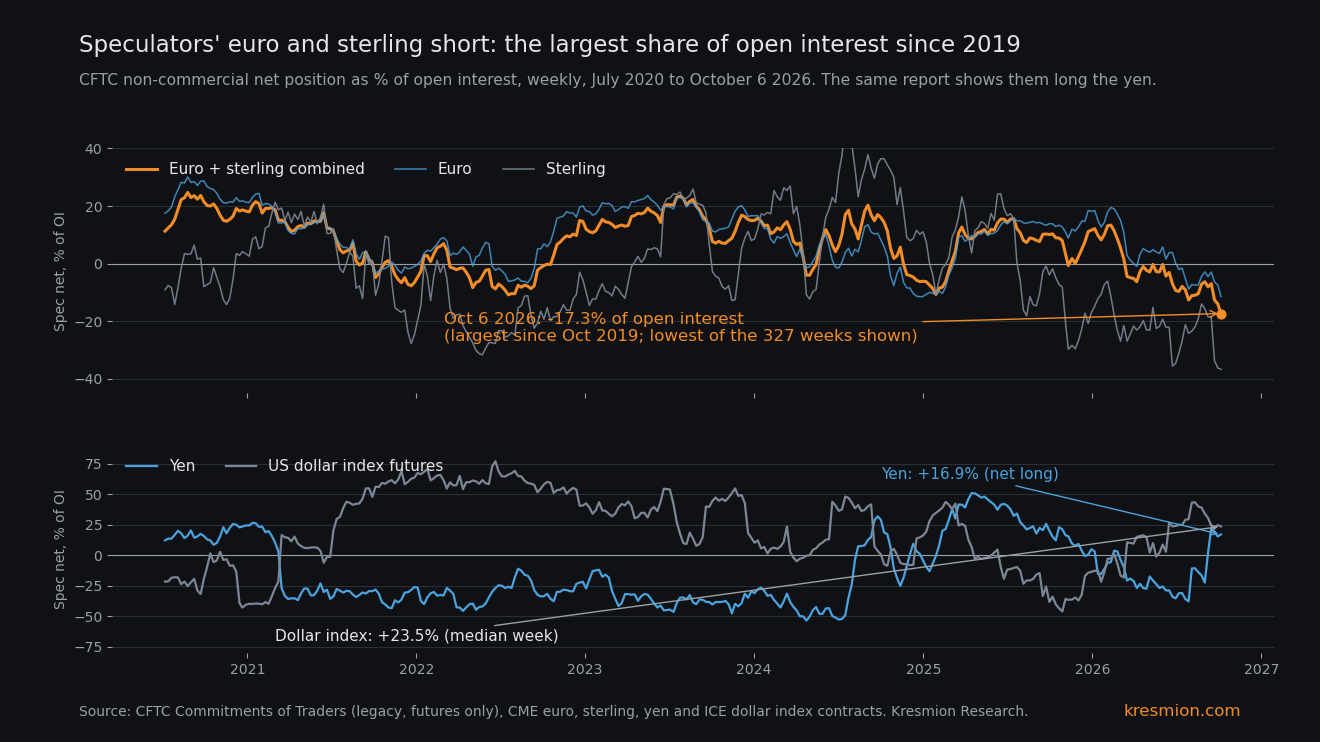
Speculators are short 342,352 euro futures contracts, the most in CFTC data back to 1999, and their euro and sterling net short is the largest since 2019. The figures come from the CFTC report for Tuesday October 6. Combined, speculators (CFTC non-commercial traders) are net short 196,943 euro and sterling contracts, 17.33% of open interest, a share last exceeded in October 2019. The shorts were added while both currencies fell, and they come in a month when the European Central Bank raised rates and markets priced Bank of England hikes. The data is a single source, and in it crowding has not reliably predicted the next move in EUR/USD.
Key takeaways
| What | Number |
|---|---|
| Euro speculator shorts, October 6 | 342,352 contracts, the most in CFTC legacy data for the contract (prior high 271,608 on February 25, 2020). As a share of open interest, 39.3%, the highest since February 2020 and far below the 64.3% of January 2012 (CFTC) |
| Combined euro plus sterling net position | -196,943 contracts on 1,136,181 open interest, -17.33%. The share was last larger on October 15, 2019 (-19.70%); the contract count was last larger on November 29, 2016 (-197,375) (CFTC) |
| Within the last 327 weeks (July 2020 onward) | Rank 1 of 327, about 2.5 standard deviations below the window's mean, and a new low three weeks running: -12.65%, -13.96%, -17.33% (CFTC via Kresmion) |
| Sterling, October 6 | Net -97,611 contracts, -36.7% of open interest, the largest share since September 2019 (CFTC) |
| Yen and dollar index | Yen net long 62,325, +16.9% of open interest, about half the 120,359 of September 15. Dollar index futures net +23.5%, a median week of 327 (CFTC) |
| Prices, September 15 to October 6 | EUR/USD 1.15485 to 1.12171 (-2.87%); GBP/USD 1.35009 to 1.32186 (-2.09%) (Kresmion closing prices) |
What the CFTC report shows
The CFTC publishes the Commitments of Traders report every Friday for positions held the Tuesday before. In its legacy futures-only format the non-commercial group is the one usually called speculators (CFTC). In the report for Tuesday October 6, euro shorts rose 40,913 on the week to 342,352 and longs rose 4,837 to 243,020, for a net short of 99,332. Euro shorts rose 106,359 contracts in three weeks, the largest three-week increase in the 327 weeks Kresmion holds. Sterling shorts reached 142,870 against 45,259 longs. FXStreet's COT summary shows the same net figures (FXStreet).
The contract-count record needs one qualifier. The euro futures market is bigger than it was, with 870,291 contracts of open interest on October 6. As a share of open interest the euro short is the highest since February 2020, and in January 2012 it reached 64.3%. CFTC history files cover the contract back to 1986, and the euro has traded since 1999.
The mechanism
An ECB hike and priced Bank of England hikes did not support either currency. The ECB raised its deposit facility rate to 2.50% in September, effective September 16 (ECB), the day the Federal Reserve raised its target range to 3.75 to 4.00% (Federal Reserve). The euro fell 2.87% over the next three weeks anyway.
Sterling shows the pattern more clearly. The Bank of England held Bank Rate at 3.75% on September 17 by six votes to three and paused gilt sales until April 2027, and sterling was sold on what Saxo called a slightly dovish reading (Saxo). By October 1 the 30-year gilt yield was above 6% for the first time since 1998, the 10-year at its highest since July 2007, and markets priced as many as four Bank of England hikes by next summer (FXStreet). GBP/USD still fell below 1.32. FXStreet's explanation: investors who expect more inflation, and who doubt the Bank of England's path, sell the bonds and the currency together. The Autumn Budget is on October 28 (TMGM).
For sterling, FXStreet read the gilt selloff as inflation expectations and Bank of England policy uncertainty that weighed on the currency instead of supporting it. For the euro, the candidate channels are the policy gap with the Fed, the French fiscal concerns FXStreet cited, and energy, with Brent near $104 and both economies importing it. FXStreet cited France's fiscal position and high oil prices as euro headwinds (FXStreet). On the US side, the 10-year Treasury yield reached its highest since 2007 in September, and Reuters reported that the prospect of higher rates lifted the dollar to multi-week highs against the euro and sterling (Reuters via GV Wire).
This is a reading of commentary and prices. The CFTC data shows positions, not motives.
Other explanations
Three alternatives compete with that reading.
Trend following. Shorts were added while both currencies fell, so the position may be following price. A momentum fund and a fund with a view on European fiscal risk leave the same footprint in a weekly count.
Policy-rate carry. On current rates the gap to the Fed's 3.875% midpoint is 137.5 basis points for the euro. That fits the euro short. It fits sterling poorly: the gap there is 12.5 basis points, and the hikes markets price for the Bank of England would narrow it.
Hedging and relative value. The legacy non-commercial group includes funds hedging European asset holdings and funds running basis or relative-value trades. A futures short can be one leg of something larger, so the net number overstates a pure directional bet by an unknown amount.
The September expiry also flattered the September 22 reading: euro open interest fell from 920,035 to 821,689 and sterling from 314,293 to 244,925 between September 15 and 22. The October 6 week is not an expiry week, open interest rose, and the euro short is a record in contracts, so the latest reading does not depend on the denominator.
The base rate
Inside Kresmion's 327 weekly reports since July 2020, the combined position ranks first and sits about 2.5 standard deviations below the mean. CFTC history is longer, and it shows bigger bets against Europe: the combined net short reached 41.0% of open interest on March 31, 2015, and 19.70% on October 15, 2019. Measured against that longer record, this is the largest such bet in six years, and there have been bigger ones. The scan behind this note covered 20 markets and three share measures; two related markets moved to extremes together, and the combined figure is derived from those two.
The evidence against
Crowding has not reliably predicted the next move in this data. Across 245 report weeks since 2022, the fifth of weeks with the largest combined euro and sterling net short saw EUR/USD 20 trading days later average -0.28%, with a median near zero, and GBP/USD -0.56%. The fifth with the largest net long saw -0.47% for EUR/USD. The middle groups averaged about +0.5%. Weekly observations with 20-day windows overlap, and with 49 weeks per group differences this size are within noise, so this is an absence of evidence either way.
The euro has not fallen further since the snapshot. EUR/USD closed at 1.12171 on October 6 and traded near 1.121 on the morning of October 12, while GBP/USD traded near 1.326 against 1.32186. The 15-trading-day fall to October 6 sat at the 3.7th percentile of such changes since 2022, so the move was already large when the report was taken.
A euro and sterling short is also a long dollar position against those two currencies. Speculators in the dollar index futures contract hold an ordinary position, net +23.5% of open interest, but that contract is small, with 51,095 contracts of open interest against 870,291 for the euro. Speculators are net long the yen, although that long has been cut roughly in half since September 15 as USD/JPY rose from 154.385 to about 158.
What would change the read
The next report comes Friday October 16 with Tuesday October 13 data (CFTC release schedule). Euro and sterling shorts that keep growing would make it four weeks running; covering would end the run. US CPI for September follows on Wednesday October 14 at 08:30 ET (BLS). After that come the FOMC on October 27 and 28 (Federal Reserve), the UK Autumn Budget on October 28, the ECB on October 28 and 29 (ECB) and the Bank of England on November 5 (Bank of England). If gilt yields and sterling start rising together, the risk-premium reading weakens. The yen long sits against a USD/JPY high of 163.864 on July 29, two days before Japan and the US bought yen together (Adnkronos).
Frequently asked questions
Is the euro short a record?
In contracts, yes: 342,352 is the most in CFTC legacy data for the contract, above the 271,608 of February 25, 2020. As a share of open interest, 39.3%, it is the highest since February 2020 and below the 64.3% of January 2012.
How big is the combined euro and sterling short?
Net -196,943 contracts on 1,136,181 of open interest, or -17.33%, in the report for Tuesday October 6. That share was last larger on October 15, 2019, and it reached 41.0% in March 2015.
Why would higher rates come with a weaker currency?
FXStreet described it for sterling in October: the 30-year gilt yield passed 6% while GBP/USD fell, because investors who expect more inflation sell the bonds and the currency together. For the euro, the candidates are the policy gap with the Fed, French fiscal worries and energy prices, and the CFTC data does not show which of these drove the shorts.
Does heavy speculator shorting predict a euro move?
Not reliably in this data. Since 2022 the most-short fifth of weeks saw EUR/USD 20 trading days later average -0.28%, and the most-long fifth -0.47%, differences within noise.
When is the next data point?
The next Commitments of Traders report is Friday October 16, covering Tuesday October 13. US CPI is Wednesday October 14 at 08:30 ET.
Sources
CFTC, Commitments of Traders, legacy report categories and historical files: futures-only non-commercial positions, report date October 6, 2026, and history back to 1986.
CFTC, Commitments of Traders release schedule: October 2026 releases.
FXStreet, COT report October 9, 2026: euro FX net -99,332 and sterling -97,611.
Federal Reserve, press release September 16, 2026: federal funds target range 3.75 to 4.00%.
European Central Bank, key interest rates: deposit facility 2.50% from September 16, 2026.
Saxo, September 17, 2026: Bank of England holds at 3.75% by 6 to 3, pauses gilt sales until April 2027.
FXStreet, October 1, 2026: 30-year gilt yield above 6%, up to four Bank of England hikes priced, GBP/USD below 1.32.
TMGM, October 7, 2026: the October 28 Autumn Budget.
FXStreet, October 2, 2026: France fiscal position and oil as euro headwinds.
Reuters via GV Wire, September 23, 2026: 10-year Treasury yield highest since 2007.
Adnkronos, August 3, 2026: joint Japan and US yen purchases on July 31.
US Bureau of Labor Statistics, October 2026 release schedule: CPI on October 14.
Federal Reserve, FOMC calendar: next meeting October 27 and 28.
ECB, Governing Council meeting calendar: monetary policy meeting October 28 and 29.
Bank of England, upcoming MPC dates: next decision November 5.